Getting into a car accident is scary, even when it’s minor. Your hands shake, your thoughts race, and it’s hard to think clearly. Knowing what to do in a car accident before it happens can protect your safety, your wallet, and your legal rights later on.
Here’s the short version. Check for injuries, get to safety, document everything, and contact your insurer. The rest of this guide breaks down each step so you’re not guessing in the moment.
Quick Answer Checklist
- Check yourself and passengers for injuries.
- Move to a safe spot if the car still drives and it’s safe to do so.
- Turn on hazard lights and call 911.
- Exchange information and photograph the scene.
- File a police report if required, then start your insurance claim.
Check for Injuries and Get to Safety
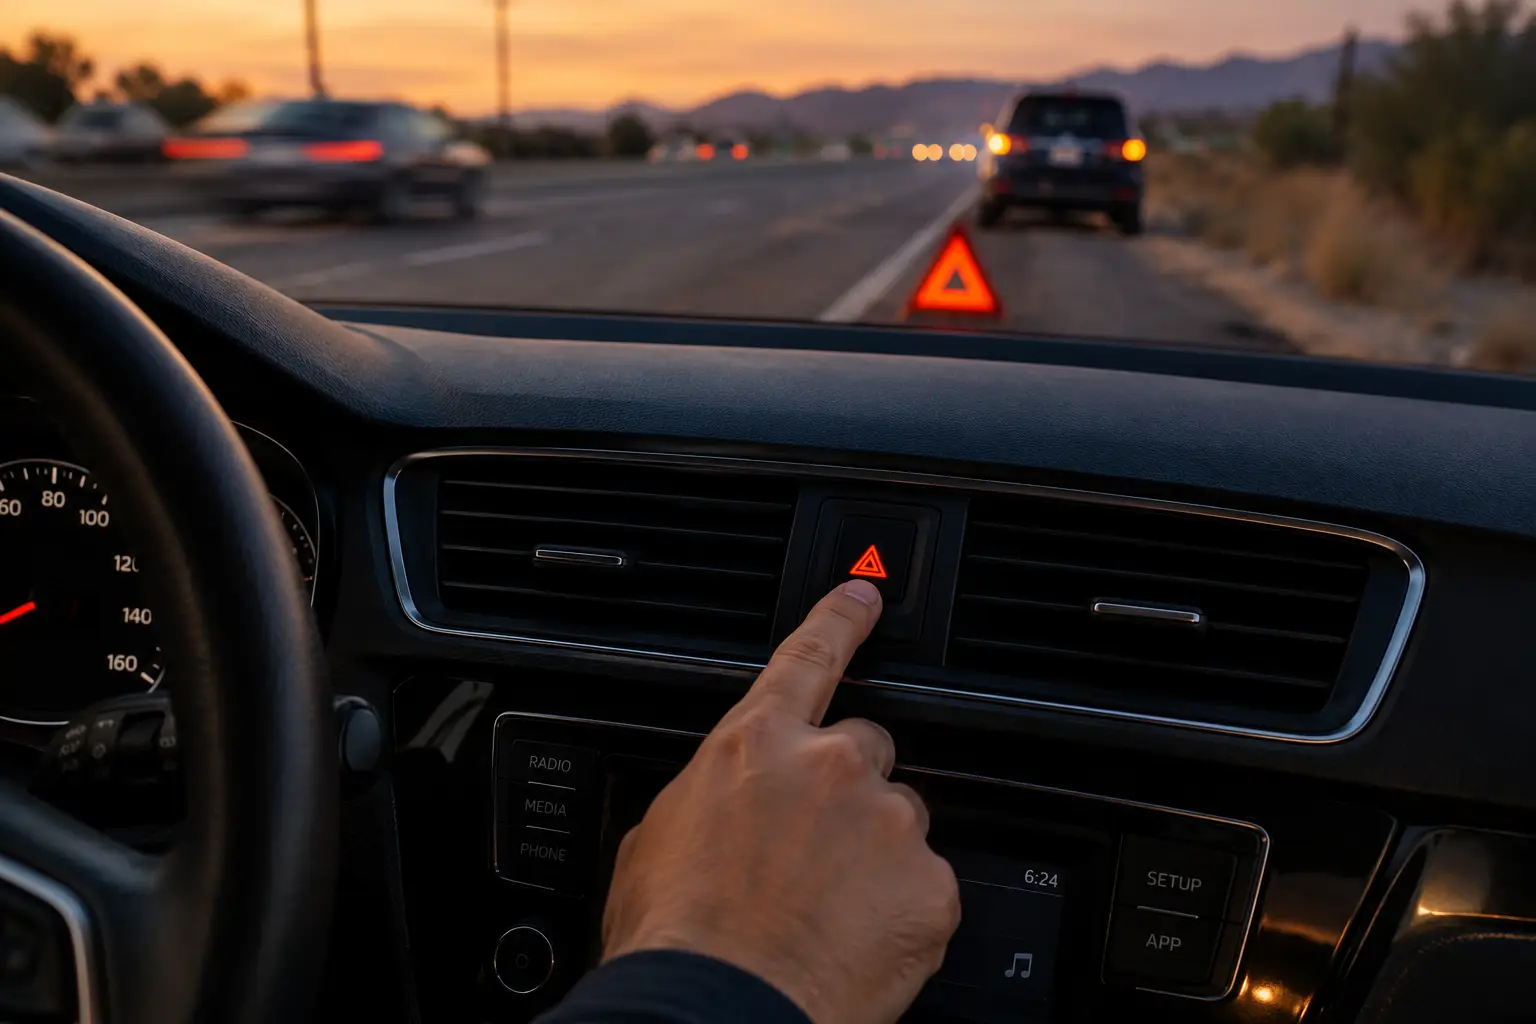
Adrenaline can hide pain for several minutes after a crash. You might feel fine and still have a real injury. Sit still for a moment and check your arms, legs, neck, and back before you move. If everyone can walk and the car still runs, move it out of traffic. Staying in a live lane after a wreck is one of the most common ways people get hurt in a second, worse collision.
Turn on your hazard lights the second the car stops moving, even before you check on anyone else. If you carry road flares or reflective triangles, set them out behind your vehicle so oncoming traffic sees you early. Then call 911. Tell the dispatcher your location, how many people are involved, and whether anyone looks hurt. Mention if an airbag deployed, since that alone can cause bruising, burns, or a broken wrist that isn’t obvious right away.
When You Can’t Move Your Car Out of the Road
Sometimes moving isn’t an option. The car won’t start, a door is jammed, or someone is pinned and shouldn’t be moved at all. In that case, stay buckled, keep your hazards on, and wait. A non-drivable vehicle sitting in a live lane is a serious traffic hazard, especially on a highway shoulder at night.
If you can safely exit through a door away from traffic, do it and get behind a guardrail or well off the roadway. If you can’t get out safely, stay put and wait for police or a tow truck. Don’t try to push a car out of traffic yourself. That’s how a fender bender turns into someone getting hit by a passing car.
Document the Scene Before You Leave
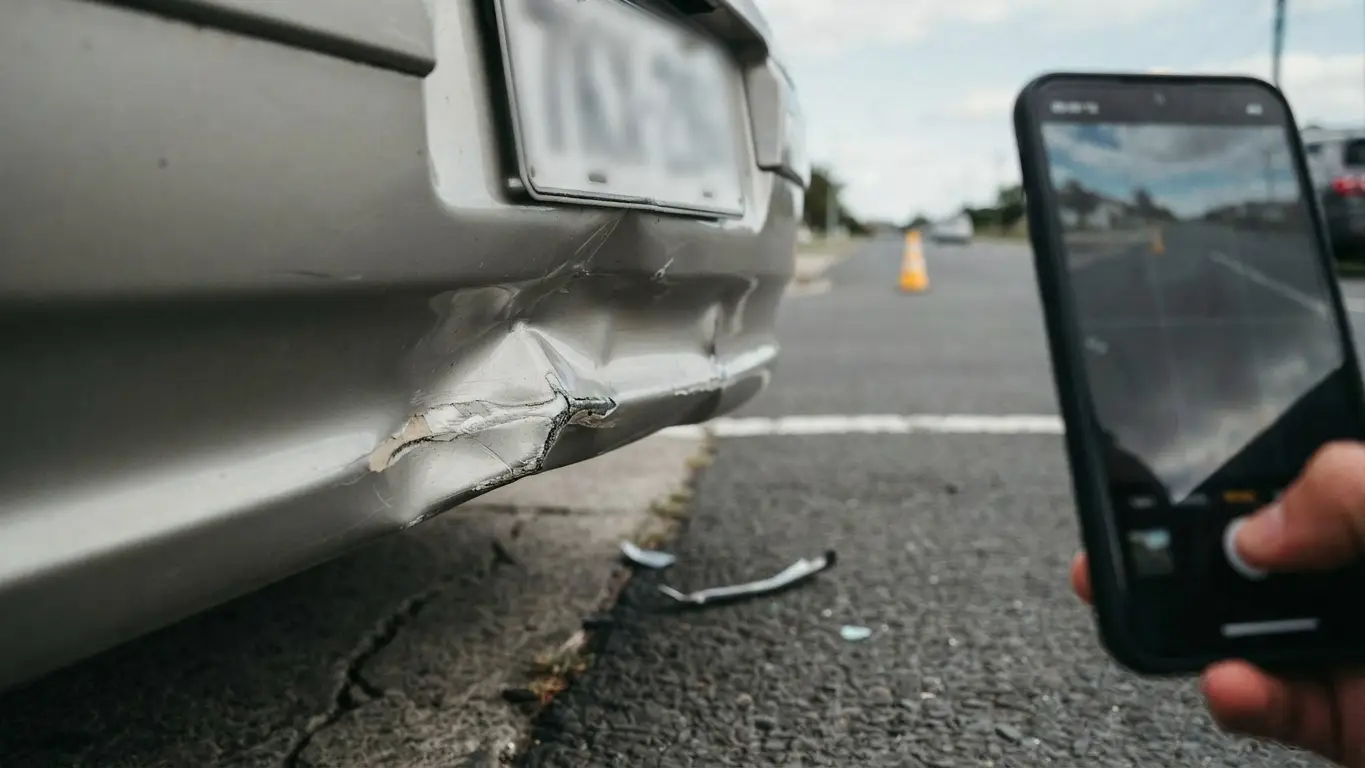
Once everyone is safe, start gathering information. This step protects you more than almost anything else you’ll do. Get the other driver’s name, phone number, driver’s license number, license plate, and insurance policy number. Take a photo of their insurance card and driver’s license if they’re willing. Write down the VIN if you can see it on the dashboard through the windshield.
Photograph the damage to both vehicles from four angles: front, back, and both sides. Photograph the full scene too, including skid marks, road signs, and traffic signals. Note the weather and time, since time-stamped photos from your phone usually record this automatically. If anyone saw the crash happen, get their name and phone number as a witness statement. People who stop to help rarely stick around long, so ask right away.
Do You Need to Call the Police?
In most states, you’re required to call the police if the crash caused an injury, a death, or property damage above a set dollar amount. That threshold varies by state, and it’s usually somewhere between $1,000 and $2,500.
In Arizona, for example, officers are required to file a written accident report when a crash results in injury, death, or property damage over $2,000, or when a citation is issued (Arizona Revised Statutes § 28-667).
Even when a crash falls under that number, calling anyway is smart. Part of knowing what to do in a car accident is understanding that a report protects you even when it isn’t required. A police report gives you an official accident report number, and it becomes the record insurance companies and the DMV rely on if the other driver later changes their story. When in doubt, call.
What to Do When You Have a Car Accident That Isn’t Your Fault
If the crash wasn’t your fault, what happens next depends heavily on your state’s insurance system. In an at-fault state, the driver who caused the crash (or their insurer) pays for damages through a liability claim. In a no-fault state, your own insurance typically covers your medical bills first, regardless of who caused the wreck, though you can still pursue the at-fault driver for serious injuries or property damage.
If the other driver had no insurance or not enough of it, your uninsured or underinsured motorist coverage is what kicks in instead. Check your policy now, before you ever need it, so you know which type of coverage you’re carrying.
If the Other Driver Takes Off
A hit-and-run leaves you with no other driver to exchange information with, so shift your focus fast. Write down as much of their license plate as you saw, even a partial one helps. Note the car’s color, make, and approximate model. If you have a dashcam, save the footage immediately before it gets overwritten.
Call the police and file a report right away. This isn’t optional here, since a report is usually required to file an uninsured motorist claim for a hit-and-run. Ask any witnesses if they caught the plate or got video on their own phone.
Getting Towed Safely: What to Check Before Anyone Hooks Up Your Car
Predatory towing scams often involve unrequested operators pressuring accident victims into costly, unauthorized impoundments, with legitimate services typically costing between $75 and $250. For secure accident recovery in the West Valley, licensed and insured operators provide upfront pricing and transparent documentation without hidden fees. You can contact Redline Roadside & Towing LLC for assistance.
Starting Your Insurance Claim
Call your insurance company the same day if you can, even for minor damage. Waiting can slow down your claim or give an adjuster reason to question it.
You’ll need your policy number, the other driver’s information, photos, and the police report number if one exists. The claims adjuster will review the damage and estimate repair costs, minus your deductible.
If repairs cost more than the car is worth, the insurer may declare it a totaled vehicle and pay out its actual cash value instead of fixing it. Get a repair estimate from a certified body shop, and don’t feel pressured to use whichever shop the adjuster suggests first. You’re allowed to choose.
What Not to Do After a Crash
A few habits can genuinely hurt your claim or your case later.
Don’t say “I’m sorry” or anything that sounds like an admission of fault at the scene. You might not have the full picture yet, and those words get quoted back to you. Don’t leave before you’ve exchanged information and taken photos, even if the other driver seems eager to go.
Don’t skip calling your insurer just because the damage looks small; hidden frame or suspension damage often costs more than it looks. And don’t assume you’re fine just because nothing hurts yet. Keep your paperwork and photos in case you need them, since most states give you a few years under the statute of limitations to file a claim if problems surface later.
Watch for Injuries That Show Up Later
Some injuries take a day or two to announce themselves. Whiplash is the classic example. Your neck feels fine at the scene, then you wake up the next morning barely able to turn your head.
Headaches, stiffness, numbness, or trouble concentrating in the days after a crash are worth a doctor visit, even if you felt okay initially. Getting checked creates medical documentation that ties your symptoms to the accident date, which matters if you end up needing a claim later. Waiting weeks to see a doctor makes it easier for an insurer to argue something else caused the injury.
FAQs
What to do in case of a car accident with no injuries?
Move to safety if you can, exchange information with the other driver, take photos, and call your insurer. Many states don’t require police for damage-only crashes below a set dollar threshold, but filing a report anyway protects you if the story changes later.
What to do if in a car accident that’s your fault?
Stay at the scene, check on everyone’s safety, and exchange information the same as any other crash. Avoid admitting fault out loud. Report it to your own insurer honestly; they’ll handle the liability claim from there.
Do I have to call the police for a minor accident?
It depends on your state’s damage threshold, often between $1,000 and $2,500. When you’re unsure, call anyway. A police report is cheap insurance against a dispute later.
What if the other driver doesn’t have insurance?
Your uninsured motorist coverage, if you have it, pays for your damages and injuries instead. This is also why filing a police report matters even in a hit-and-run or uninsured-driver situation.